Sell and Buy a House at the Same Time in Salem
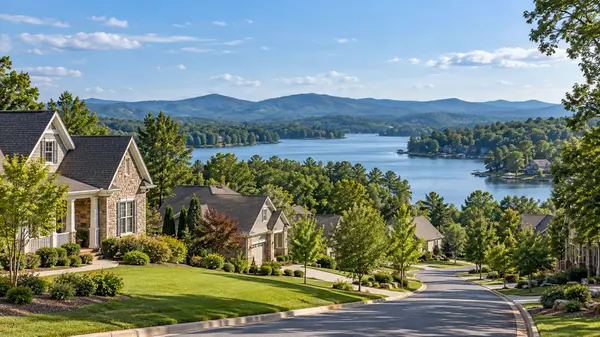
Selling and buying a house at the same time in Salem is possible when financing, sale proceeds, and contract dates are planned before either transaction becomes urgent. Salem is a town in Oconee County, South Carolina, and a move involving lake-oriented property, a particular lot, or a limited replacement-home search can add timing pressure. Start by confirming available equity, a lender-supported purchase range, your preferred move date, and a backup plan for any gap between closings.
Why Timing Matters in Salem
-
Market pace: A dated, eligible Salem median-days-on-market figure was not available for this article, so sellers should evaluate current showing activity and competing properties before setting a move deadline.
-
Market balance: A verified Salem months-of-supply figure was not available, which means conditions may differ substantially by price range, property type, and location.
-
Closing window: Closing dates are negotiated in each contract, so the sale and purchase timelines need to be coordinated rather than assumed to match.
-
Local factor: Lake-oriented homes, vacant land, and homes with specific access or view characteristics can create a narrower replacement-property search.
-
Rate benchmark: The national average 30-year fixed mortgage rate was 7.40% on October 8, 2026. (Freddie Mac Primary Mortgage Market Survey, October 8, 2026.)
Salem Market Snapshot for 2026
| Metric | Value | Source |
|---|---|---|
| Median home sale price | A dated, verified Salem closed-sale median was not available for use | Local market data should be reviewed before listing or offering |
| Median days on market | A dated, verified Salem measure was not available for use | Local market data should be reviewed before listing or offering |
| Months of housing supply | A dated, verified Salem supply measure was not available for use | Local market data should be reviewed before listing or offering |
| Average 30-year fixed mortgage rate | 7.40% on October 8, 2026 | Freddie Mac Primary Mortgage Market Survey |
Why Selling and Buying at the Same Time in Salem Needs a Plan
Selling and buying a house at the same time in Salem needs a written plan because the money from one closing may be needed for the next one, while the dates rarely line up perfectly. Your current-home proceeds can affect the down payment, reserves, and loan structure for the replacement purchase. Meanwhile, the seller of the home you want may need confidence that your purchase can close on schedule.
The first risk is a cash gap. Equity can remain tied up until your sale closes, leaving less flexibility for a down payment or closing costs. The second is a housing gap if your home sells before you secure a replacement. The third is payment overlap when you buy first and your current home takes longer than expected to sell.
Salem’s housing choices can be especially specific for homeowners seeking waterfront proximity, a certain lot, or a particular property style. That makes preparation important before an offer deadline arrives. Review your likely net proceeds, remaining loan balance, purchase budget, and the range of Salem homes and property listings that meet your essential criteria.
Your Three Paths at a Glance
| Strategy | Best When | Biggest Risk |
|---|---|---|
| Sell First with rent-back | You need completed sale proceeds before purchasing the next home. | A short post-closing stay can create pressure to find a replacement quickly. |
| Buy First with a bridge loan or HELOC | You have strong equity, qualifying income, and a conservative repayment plan. | You may carry two housing payments until the current home sells. |
| Contingent Offer | You need your current home to sell before committing to a purchase. | A seller may choose an offer without a home-sale condition. |
Sell First in Salem With a Rent-Back Agreement
Selling first provides the clearest financial picture because your existing home closes before you commit to the next purchase. Under this approach, you prepare and list the current home, accept an offer, and negotiate a post-closing occupancy agreement that allows you to remain temporarily while completing your next purchase or arranging temporary housing.
A rent-back agreement is negotiated, not automatic. Its terms should identify the possession date, daily or periodic occupancy payment, security deposit if required, insurance responsibilities, property-condition expectations, and the consequences of staying after the agreed deadline. The parties should have the agreement reviewed through the appropriate closing process before signing.
This path can suit Salem homeowners who need sale proceeds for their next down payment or who do not want to carry two mortgage payments for an uncertain period. It also replaces an estimate of proceeds with an actual number, making the next-home budget more dependable. A realistic sale-price discussion and net-proceeds estimate should happen before the replacement-home search becomes urgent.
The downside is reduced flexibility after closing. A limited occupancy period may not leave enough time to find a home with the desired location, lake access, lot characteristics, or layout. If the right home does not become available, you may need storage, temporary housing, and a second move.
No dated, eligible Salem dataset establishes a standard local rent-back duration or acceptance rate. Duration, cost, and buyer willingness should be treated as transaction-specific terms.
Buy First in Salem Using a Bridge Loan or HELOC
Buying first can work when you have substantial usable equity and a lender confirms that the temporary payment structure is affordable. A bridge loan is short-term financing intended to cover the period between buying a replacement home and receiving proceeds from the current home. A home equity line of credit, commonly called a HELOC, is a revolving line of credit secured by equity in the current property.
Both options require lender review of income, debt obligations, credit, available equity, property value, and the proposed purchase. They can also add interest costs, lender fees, and payment exposure beyond the new mortgage. Ask the lender whether the underwriting calculation includes both housing payments, whether the current home must be listed before approval, and what repayment event ends the temporary financing.
Banks, credit unions, and licensed mortgage lenders may offer equity-based or short-term financing options, but program availability and qualification standards vary. The 7.40% national 30-year fixed benchmark reported on October 8, 2026 highlights why you should use written lender terms rather than an assumed rate or payment.
This strategy is most practical when your household can afford a conservative scenario if the current home takes longer to sell than expected. It may also fit homeowners who have a compelling replacement-home opportunity and enough reserves to absorb timing changes without forcing a rushed sale.
Before proceeding, compare the payment implications, repayment requirements, estimated sale proceeds, and a backup plan if the original home does not close on the preferred schedule.
Use a Contingent Offer for a Salem Purchase
A contingent offer protects you by making the purchase of the next home dependent on the sale of your current home. It can reduce the risk of being required to close before your proceeds are available or before you are comfortable carrying another housing payment.
Whether a seller accepts that condition depends on the property, price, competing interest, and the strength of your existing listing. A verified current Salem supply or closed-sale timing measure was not available for this article, so it would not be reliable to say contingent offers are routinely accepted or rejected. In practice, a seller can evaluate a contingency more confidently when your home is already listed, appropriately priced, and supported by clear documentation of available equity.
Some sellers may request a kick-out clause. This clause allows the seller to continue marketing the home and gives you a defined period to remove the home-sale condition if another acceptable buyer appears. If you cannot proceed within that period, the seller may be able to move forward with the other buyer.
Strengthen a contingent offer by preparing your current home before beginning an intensive search, organizing lender documentation, and defining the sale condition clearly. The contract should state what must occur, when it must occur, and what documentation will confirm it. Clear deadlines make the offer easier for both sides to assess.
Which Path Is Right for You?
-
Strong equity and a time-sensitive replacement home: Buying first with a bridge loan or HELOC may fit when a lender confirms you can manage the temporary payment exposure.
-
Sale proceeds needed for the next purchase: Selling first with a rent-back or temporary-housing plan can provide the greatest financial clarity.
-
Limited ability to carry two housing payments: A contingent offer may be the better fit because it ties the purchase to the sale of your existing home.
How to Sell and Buy a House at the Same Time in Salem: Step by Step
Selling and buying a house at the same time in Salem works best when financing, listing preparation, and contract timing are decided in that order.
-
Get pre-approved using the full payment picture. Ask the lender to assess the proposed mortgage alongside your existing housing payment, savings, debt, and any equity-based financing.
-
Confirm your usable equity. Review a realistic sale range, remaining loan payoff, anticipated transaction costs, and the cash required for the replacement purchase.
-
Choose a strategy and timeline. Decide whether you will sell first, buy first, or make a contingent offer, then select a backup housing option before negotiations begin.
-
Prepare and list the current home. Establish the pricing approach, launch date, showing plan, and communication process so the property is ready when a suitable replacement appears.
-
Search around nonnegotiables. Separate essential Salem features, such as location, access, lot type, or property layout, from preferences that can change if timing becomes tight.
-
Coordinate dates in both contracts. Align financing, possession, and closing terms deliberately instead of expecting both transactions to close together automatically.
-
Document the gap solution. A rent-back, temporary-financing arrangement, or sale contingency should include clear deadlines, responsibilities, and fallback options.
-
Plan the move before closing. Reserve movers or storage, update insurance, and decide where you will stay if either closing is delayed.
A simultaneous move calendar should track lender milestones, contract deadlines, possession dates, and moving commitments in one place. Since a dated Salem average-days-on-market figure was not available for this article, build enough flexibility into the plan for property-specific demand and negotiation changes.
What Makes Salem Challenging but Manageable
Salem can make a simultaneous move more complex because replacement homes are not interchangeable. A buyer looking for lake-area proximity, a specific lot, or a particular home style may have fewer workable alternatives than a buyer whose search can include many similar properties.
The town’s market can also vary by property type and location. A home with a distinct setting may attract a different buyer pool than a conventional residence, while a replacement search may depend on the availability of a narrow set of features. Without a dated, eligible Salem inventory measure, broad claims about local supply would not be reliable.
The practical response is to begin preparation early. Make the current home ready to list before a replacement opportunity appears, organize financing documents in advance, and identify at least two ways to handle a gap between closings. Homeowners considering a premium or waterfront purchase should define their must-have criteria early, then avoid committing to a sale timeline that leaves no room for a limited replacement search.
Household carrying costs also vary by property type, insurance needs, utilities, and location. Set a lender-supported payment ceiling before accepting an offer on the current home, especially if temporary financing or overlapping payments are possible.
Simultaneous Transaction Checklist for Salem Homeowners
-
Confirm your equity position. Estimate likely proceeds after the loan payoff and expected transaction costs.
-
Obtain financing guidance. Ask a lender to evaluate the payment if both homes overlap temporarily.
-
Set a maximum purchase budget. Base it on lender-confirmed terms rather than an assumed sale price.
-
Choose your transaction path. Decide whether you will sell first, buy first, or use a sale contingency.
-
Prepare the current home early. A ready-to-list property gives you more options when a suitable replacement appears.
-
Create a document folder. Keep loan information, income documents, insurance details, and property records accessible.
-
Define your must-have criteria. Focus the Salem search on the location, property type, and features that cannot be changed later.
-
Plan for a housing gap. Identify temporary housing, storage, or a negotiated post-closing occupancy option before it becomes urgent.
-
Coordinate every deadline. Track contract dates, lender milestones, possession terms, and moving commitments in one calendar.
-
Keep a financial reserve. Preserve funds for moving, temporary housing, lender costs, and timing changes.
Ready to Make Your Move in Salem?
Suzanne (Sue) Brown coordinates simultaneous sales and purchases for Salem homeowners, helping align financing, listing preparation, negotiations, and closing dates. Call or text +1 (864) 400-7994, or email savvyrealtysc@gmail.com, to discuss the approach that fits your timing, equity position, and replacement-home goals.
FAQ: Selling and Buying a Home at the Same Time in Salem
Can I buy a house before selling mine in Salem?
Yes, if you have sufficient savings, qualifying income, or lender-approved equity financing to fund the purchase before your current home closes. A bridge loan or HELOC may help, but the lender must confirm that the temporary payment exposure works for your finances.
How do I avoid paying two mortgages at once?
Selling first and negotiating a rent-back agreement can reduce payment overlap while you search for the next home. A purchase contingency can also make your purchase dependent on the closing of your existing home.
How long does it take to sell and buy at the same time in Salem?
A verified current Salem closed-sale timeline was not available from a dated eligible local source for this article. Your schedule will depend on property response, financing, negotiated closing dates, and whether you use a rent-back, temporary financing, or contingency.
Should I sell or buy first in Salem’s current market?
Selling first may be more suitable when you need completed sale proceeds for the next down payment or cannot comfortably carry overlapping housing payments. Buying first can work when strong equity, reserves, and lender-approved financing provide flexibility.
What is a rent-back agreement and is it common in Salem?
A rent-back agreement lets a seller remain in the home for an agreed period after closing while paying the buyer under stated terms. No dated, eligible Salem acceptance-rate figure supports a broad claim about how common these agreements are locally, so availability should be negotiated case by case.
Categories
Recent Posts